When policy rates shift, portfolios labelled “defensive” often reveal hidden duration bets that were never authorised in the investment policy statement. Clients experience mark-to-market losses that feel like equity drawdowns, yet minutes from prior meetings show no discussion of term risk. The failure is usually governance, not mathematics.
What duration actually controls
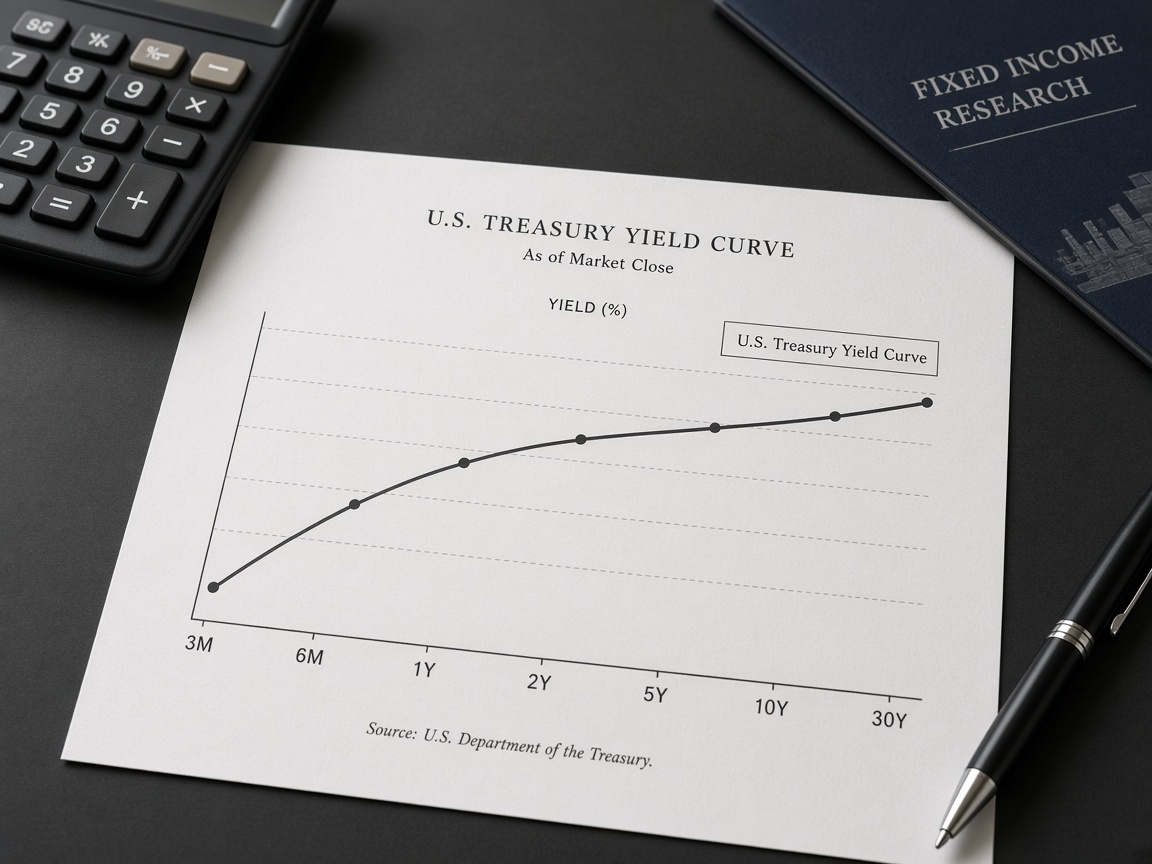
Duration measures sensitivity of bond prices to interest rate changes. A portfolio with effective duration of six years will typically move roughly six per cent in price for a one per cent parallel shift in yields—before credit spreads move independently. In Australia, many investors mentally anchor on cash and term deposits while holding funds with materially longer portfolio duration through corporate and government bond sleeves.
We observe three recurring gaps: (1) IPS language that says “defensive” without numeric duration or credit quality bands; (2) use of multi-sector funds where duration drifts with manager positioning; (3) confusion between income and stability of capital, leading retirees to accept price volatility they believed they had outsourced.
Our view at URIAH INVESTMENT PTY LTD
We require defensive sleeves to state a target duration range, maximum single-step extension, and the party responsible for monitoring (client, adviser, or platform). When rates fall and funds extend automatically to maintain yield, we treat that as a mandate change requiring documentation—not a silent benefit. Conversely, when rates rise, we resist reflexive shortening unless liquidity needs have changed; otherwise clients crystallise losses and forfeit reinvestment at higher yields without a plan.
For clients with near-term spending, we separate capital certainty instruments (cash, short deposits, very short government exposure) from return-seeking fixed income with explicit risk budget. Blending them in one line item in reporting is, in our experience, how families get surprised.
Practical steps for mandate writers
- Express defensive allocation as ranges with duration and average credit rating, not labels.
- Stress test ±100 bp rate moves in quarterly reports alongside equity scenarios.
- Record manager changes that alter duration more than 0.5 years as IPS exceptions.
- Align cash flow ladders with maturity buckets rather than fund names.
Past rate cycles do not predict future paths. To discuss duration rules for your mandate, see our services or request a proposal.